

Sezzle: Buy Now, Pay Later
by Sezzle Mobile
4.5
- Safety
- 100% Safe
- Category
- Shopping
- Ratings
- 4.5
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Sezzle is a shopping app from Sezzle Mobile that lets me divide eligible purchases into installments instead of paying the entire amount at once. That basic idea is easy to understand, but the real question is whether it remains useful after the excitement of trying a new payment option wears off. In my experience, its value depends less on browsing and more on whether I can use installment payments without turning ordinary shopping into a habit of carrying too many commitments.
The app is free to download, aimed at everyone, and available for devices running Android 7.0 or later. It has been around since March 21, 2019, and the current version is 5.2.2. Its audience is already substantial, with more than five million installs, a 4.5 average from roughly 112 thousand ratings, and around 15 thousand written reviews. Those figures suggest that this is not a short-lived experiment, but popularity alone does not make deferred payments a good fit for every budget.
From an appealing first purchase to a lasting shopping habit
I find the first purchase most useful when it starts with a need, not with the appeal of splitting a bill. This section looks at how that initial convenience can either support a deliberate shopping routine or quietly encourage extra spending, then turns to the habits that help the app remain manageable over time.
Why the first week feels convenient
The strongest first impression is simplicity. When I am looking at a purchase that would be uncomfortable as one immediate charge but manageable in smaller portions, splitting it into four or five interest-free payments can make the decision feel less abrupt. The app’s core purpose is clear, and that clarity matters when I am already focused on choosing an item rather than learning a complicated financial tool.
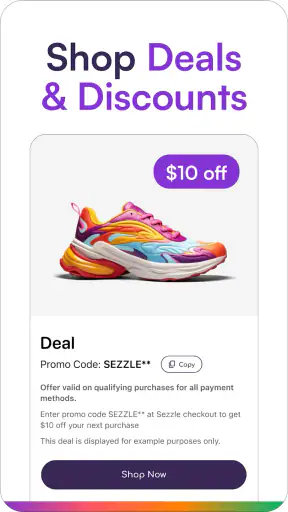
I also like the psychological difference between using a payment plan intentionally and applying for a traditional form of credit. Sezzle presents itself as part of the shopping process, so it can feel more approachable for a planned purchase such as clothing, household supplies, or a replacement item. Rewards and the ability to pay over time add reasons to return, although I would treat those extras as conveniences rather than reasons to buy something I did not already need.
A realistic example would be replacing a worn pair of shoes before a scheduled trip. Paying the full amount immediately might interfere with other bills that week, while four scheduled payments could fit more comfortably into money I already expect to receive. Used that way, the app can smooth timing without changing the underlying decision. The important part is that I would make the purchase first and use the payment option second, not browse until an installment amount makes an unnecessary item look harmless.
The practical questions I would answer before checking out
The first question is not simply whether a payment can be divided. I would ask whether the full purchase is already covered in my wider budget. An installment can look small in isolation while several active purchases quietly add up. Before confirming anything, I would write down the total amount, the number of future payments, and the dates on which those payments will matter to me.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I would also check whether the purchase is genuinely suitable for delayed payment. A necessary replacement or planned seasonal expense can make sense. A spontaneous treat, an item with uncertain sizing, or something I may return deserves more caution. Returns and refunds can create a timing gap between the retailer and the payment schedule, so I would keep track of both rather than assuming that changing my order automatically settles every installment.
Another useful habit is to keep the app for planning rather than constant browsing. If I open it only when I have a specific purchase in mind, rewards and payment flexibility remain secondary tools. If I use it as an entertainment feed, the convenience can encourage more frequent shopping. That distinction is one of the clearest differences between a helpful payment assistant and a source of financial fatigue.
Where it sits beside ordinary alternatives
Compared with paying by debit card, Sezzle offers more timing flexibility but also creates future obligations. A debit card gives me a clearer immediate picture of what has left my account. Compared with a credit card, an installment plan can feel more defined because the purchase is divided into a known sequence, while a credit balance may continue from month to month. However, a credit card may be more familiar for handling returns, consolidating transactions, or earning benefits that matter to a particular user.
Compared with saving first, Sezzle is less financially comfortable because the purchase happens before the money has fully accumulated. Saving avoids the risk of overlapping commitments, even though it requires more patience. I see the app as most useful in the narrow space between those options: a planned purchase that I can afford, where timing is awkward, and where I am disciplined enough to reserve the money for each scheduled payment.
What makes the first experience less effortless
The app does not remove the need to pay attention. I still need to understand the checkout total, remember upcoming installments, and make sure the payment method connected to the purchase is ready. Any payment service can feel frictionless during checkout and demanding later, especially when several purchases have different schedules.
There is also a difference between an interest-free plan and a completely consequence-free purchase. Even when interest is not added to the planned payments, a missed or mishandled payment can create stress, and the exact experience may depend on the transaction and account circumstances. I would never interpret “interest-free” as permission to spend beyond what I can reliably cover.
How rewards affect the decision
The rewards element can add recurring interest, but I would judge it by the value of the reward after considering the purchase itself. A discount or benefit is not a saving if it persuades me to place an order I would otherwise skip. The best use is to apply a reward to something already in my plan, then compare the final cost with the normal alternatives rather than focusing on the reward label.
This is also where the app can differ from a standard retailer app. A retailer’s own loyalty program may be better for repeat purchases from one store, while Sezzle is more useful when payment flexibility is the main reason I am using it. I would not collect several shopping programs automatically. I would keep this one only if its payment scheduling and rewards repeatedly solve a real problem.
Does it still matter after the novelty fades?
After the first few purchases, the novelty of splitting a bill disappears. That is not necessarily a weakness. In fact, a payment app earns a permanent place on my phone when it becomes boring in the best way: I know why I am opening it, I can review what I owe quickly, and it helps me make a planned purchase without encouraging constant browsing.
The recurring value comes from predictable situations rather than daily use. A seasonal clothing purchase, a necessary home item, or a larger planned order may justify returning to the app. If my shopping is mostly small and routine, paying directly is probably simpler. A tool designed for occasional payment flexibility does not need to be opened every day to be useful.
The maintenance work behind the convenience
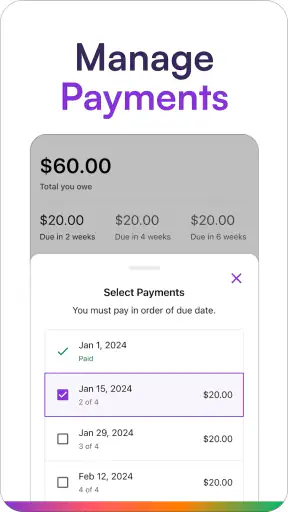
My main maintenance task would be reviewing active plans regularly. I would look at upcoming payments before making another purchase, especially around rent, utilities, travel, or other dates when my account is already under pressure. A simple personal note or calendar reminder can help, but I would still treat the app’s own payment information as the place to verify the current schedule.
I would also review completed and active purchases separately. That prevents an old order from blending into a new one and makes it easier to spot a total that no longer matches my memory. This small separation is a surprisingly useful workflow: I can decide whether I have room for another commitment without relying on the size of the next single payment.
Returns deserve their own check. If I send something back, I would keep the order confirmation and follow the retailer’s return process while watching the installment status. I would not assume that shipping an item back instantly cancels the payment arrangement. That extra tracking is a maintenance cost that does not exist in quite the same way when I pay once with cash or a debit card.
Device compatibility is another practical point. Since the app supports Android 7.0 and later, it remains accessible on many older Android phones, which is helpful for people who do not replace devices often. Still, I would keep the app updated when possible, because payment-related software is not something I would want to leave neglected for long. The current release is 5.2.2, so checking that my installed version is current is a sensible routine.
Where users may experience fatigue
The first source of fatigue is mental accounting. Four or five smaller payments can be easier to handle, but they can also make the total feel less visible. If I repeat the process across several orders, I may start thinking in weekly fragments instead of the complete amount I have committed. That is the central trade-off: convenience at checkout can require more attention afterward.
The second is notification and account attention. A payment service naturally asks me to monitor schedules, payment methods, and order status. Someone who wants shopping to be entirely passive may find that responsibility annoying. The app is not difficult because it has too many entertainment features; it is demanding because financial commitments reward regular checking.
A third source of fatigue is the temptation to use installment availability as a shopping limit. If I decide that an item is affordable only because the first payment looks manageable, I am using the feature backward. The right limit is the full purchase and its effect on my budget, not the smallest amount displayed during the decision.
Rewards can contribute to the same problem. They make returning feel productive, but repeated rewards are still attached to purchases. I would set a personal rule that rewards can improve a planned order but never create the reason for the order. That rule keeps the app from becoming a shopping trigger disguised as savings.
Who should use it and who should skip it
I think Sezzle is best for someone with predictable income, a clear reason for the purchase, and enough room in the budget to cover every scheduled payment. It can be especially practical when the timing of a necessary purchase is inconvenient but the total cost is already understood. The free price also lowers the barrier to trying it, although free access should not be confused with free spending.
I would be more cautious if my income changes frequently, if I already have several installment plans, or if I often forget automatic payments. In those situations, the additional schedule may create more stress than value. Someone rebuilding a budget may be better served by saving first and using a direct payment method that shows the full cost immediately.
I would also skip it for impulse shopping. The app cannot fix a purchase that should not happen, and splitting that purchase can make it easier to repeat. For large decisions that require extensive comparison, a credit card or direct financing arrangement may offer a more familiar record or a better-suited structure, depending on the user’s circumstances. Sezzle is not a universal replacement for every payment method.
My long-term verdict
After the novelty fades, I still see a place for Sezzle, but it is a specific place. Its lasting value comes from controlled, occasional use: I choose an item for a good reason, confirm that the complete cost fits my budget, and use the installment schedule to manage timing. The app earns its space when it reduces a real short-term mismatch between purchase date and available cash without encouraging additional shopping.
It does not earn that space for someone who wants the simplest possible money routine. Paying directly is easier to understand, easier to reconcile, and less likely to leave several future commitments competing for attention. Saving first is safer for anyone whose budget is already tight. A traditional credit card may also be preferable for users who value one consolidated statement or already have a disciplined system for paying balances.
My recommendation is therefore measured rather than enthusiastic: use Sezzle as a planned payment tool, not as permission to stretch your budget. I would install it for a specific need, review the complete schedule before confirming, keep returns organized, and reassess after a month or two. If it consistently helps with planned purchases and remains easy to monitor, the recurring value is real. If it makes me browse more, forget future payments, or think only about small amounts, I would remove it and return to paying directly.
That balance is what makes the app worthwhile for the right person. Sezzle Mobile has built a shopping app around flexibility, rewards, and installment payments, and its strong adoption shows that many shoppers find that combination useful. For me, its best quality is not making every purchase feel easier. It is giving me another option when a purchase is sensible but the timing is inconvenient, while still leaving the responsibility for the full decision firmly in my hands.
Pros
- No interest fees on purchases.
- Easy-to-use interface for quick setup.
- Supports a wide range of retailers.
- Flexible payment scheduling options.
- Enhances budgeting with spending controls.
Cons
- Limited to participating retailers only.
- Requires approval for each purchase.
- Late fees apply for missed payments.
- May affect your credit score.
- Not available in all countries.
FAQs for Sezzle: Buy Now, Pay Later
What is Sezzle and how does it work?
Sezzle is a "Buy Now, Pay Later" app that allows users to split their purchases into four interest-free payments over six weeks. Once you select Sezzle at checkout, the first payment is made upfront, and the remaining three payments are automatically scheduled. This helps in budgeting and managing expenses without incurring interest.
Does using Sezzle affect my credit score?
Sezzle performs a soft credit check when you sign up, which does not affect your credit score. However, missing payments or failing to meet your obligations could potentially impact your credit report. It’s important to keep track of your payment schedule to maintain a good standing.
What are the eligibility requirements for using Sezzle?
To use Sezzle, you must be at least 18 years old, have a valid U.S. or Canadian phone number, and possess a debit or credit card for payments. Additionally, you need to have a positive credit history and sufficient funds in your account to cover the first installment.
Are there any fees associated with using Sezzle?
Sezzle is free for users who make their payments on time. However, if a payment fails, a reactivation fee may be charged. It’s crucial to ensure that your account has sufficient funds to avoid any additional charges and to maintain smooth transactions.
Can I use Sezzle for any type of purchase?
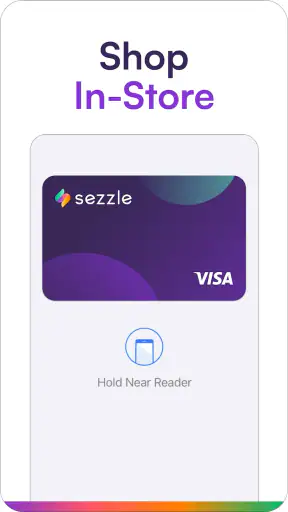
Sezzle is available at numerous participating online and in-store retailers. However, it may not be accepted everywhere. Always check if a retailer supports Sezzle before planning your purchase. You can find a list of participating retailers on the Sezzle app or website.

Sezzle: Buy Now, Pay Later
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via info@sezzle.com, visit https://sezzle.com, or review their https://legal.sezzle.com/privacy.










